

A founder wrote to me a few weeks ago, wondering about SAFEs versus convertible notes. Somewhere in the middle of it they mentioned that the angels they’d been talking to were all saying a version of the same thing: we use SAFEs, but we hate them.
I know exactly what they’re reacting to.
It isn’t the document. Nobody hates a lawyer-free five-page document. What they hate is showing up for a priced round and finding a cap table littered with SAFEs issued at four different caps on four different terms — and doing the arithmetic and realizing there isn’t room for everybody.
It isn’t a loan
When I first started helping founders raise money, the standard vehicle was the convertible note. Basically a loan with benefits. There’s interest, there’s a maturity date, and there are obligations. Because if the priced round hasn’t happened by the time the due date arrives, you get to have a very uncomfortable conversation with an investor who has turned into a creditor.
But the pendulum has swung — and now almost everyone uses a SAFE. It isn’t a loan. It isn’t debt, and it isn’t equity. It’s simply a promise: you take my money now, and when the company finally sells stock at a real price, I get shares, usually at a discount or capped at some valuation as a reward for going first. No interest. No due date. Nothing owed if that day never comes.
For a founder raising a small amount quickly, that’s a good trade. But notice what got deferred. The one thing nobody settles, on the day the money actually moves, is the actual price. And with the post-money version that’s now standard, the investor’s worst case percentage locks the moment they sign — their check divided by the cap.
I’ve done that division on every SAFE I’ve ever signed. Not once did it occur to me to ask a founder whether they had done it too.
Four decisions, none of them hard
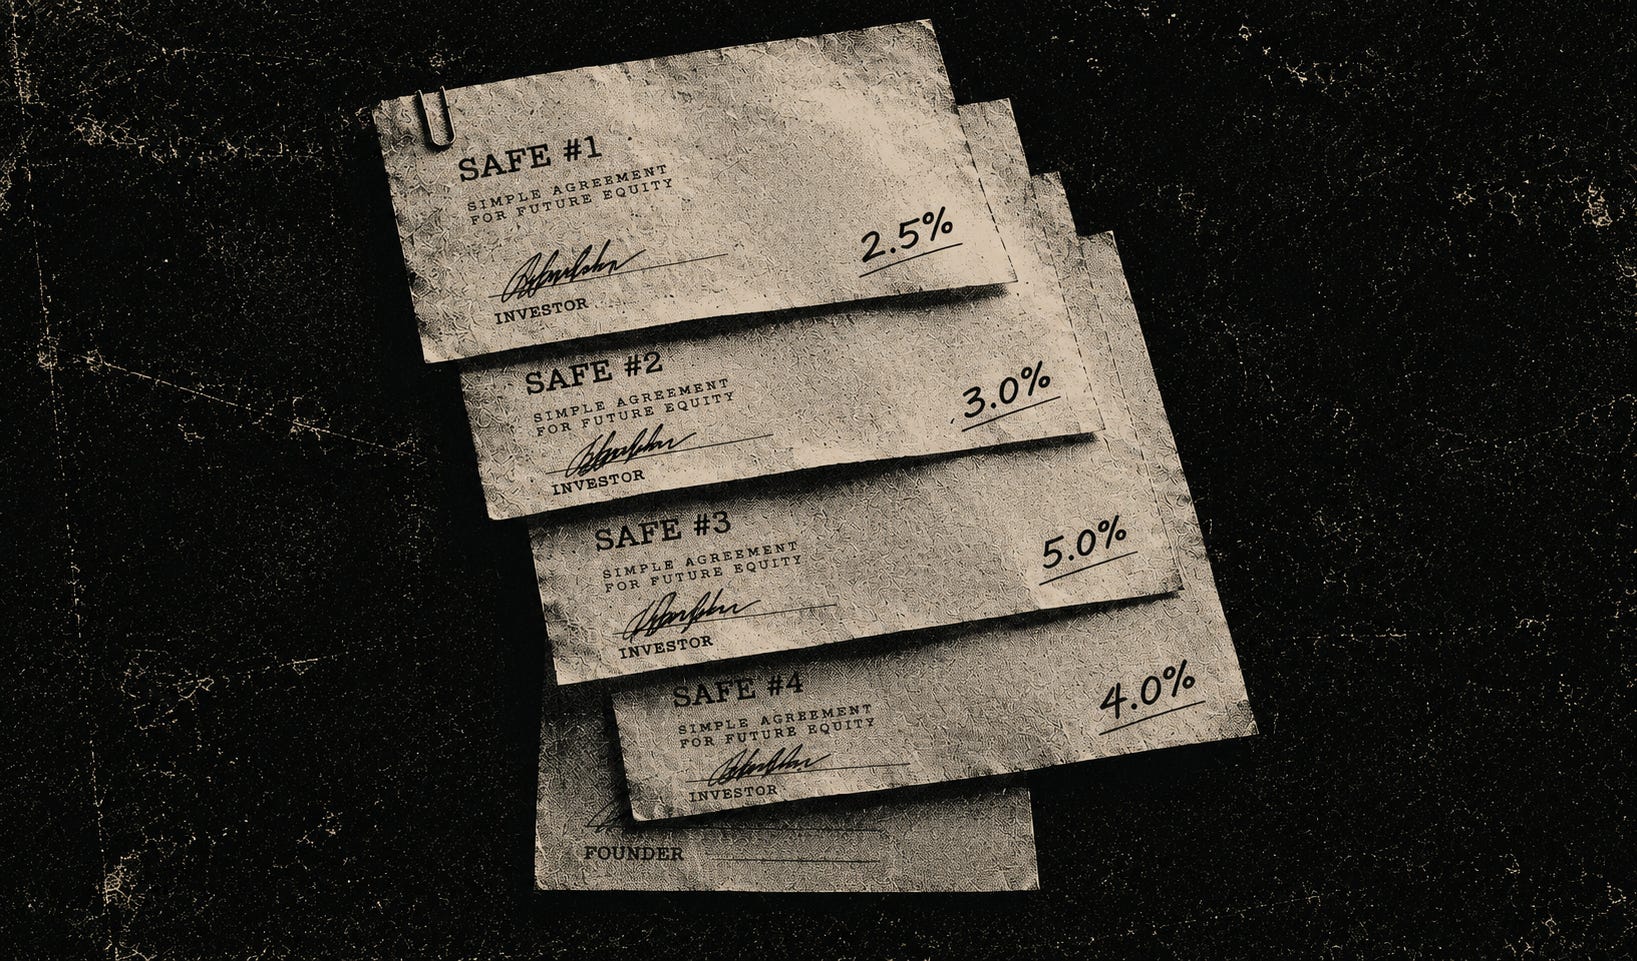
You raise $250K on a SAFE. Good day. Another $300K a few months later — slightly higher cap — you’re making progress. Then somebody offers $500K but wants a different cap, and you take it, because hey, $500K. Then a fourth with a side letter, or an MFN, because that investor’s lawyer asked and arguing wasn’t worth two weeks.
Four decisions, each one painless, because nobody was sitting across the table saying out loud what percentage of your company they’re buying. Each of those investors knows their own number — it’s their check divided by the cap. What nobody is doing is adding them all up.
Then you get to your priced round. All those promises convert into actual shares. The new investor wants twenty percent. You need an option pool, carved out before their money goes in, not after. And suddenly you discover you own considerably less of your company than you thought you did.
That’s not a SAFE problem. That’s a founder not paying attention to the numbers problem.
The email nobody wants to write
I’m an investor, via SAFE, in a company where exactly this happened. Real customers, real revenue, a product people actually want. When they went to price a round, the pieces added up to more than a hundred percent of the company. Something had to give, and it was the earliest, smallest checks.
The seat I keep thinking about isn’t mine, though. It’s the founder’s. She spent a week writing to more than a hundred people who’d backed her when the thing was mostly a hope, telling each of them their position was getting cut roughly in half. She wasn’t being greedy. By the time everyone sat down in that room there were no good options left — they’d been used up three years earlier, by a hundred small decisions that took nine minutes each.
The 1% that wasn’t 1%
There’s a quieter version of this.
A founder I was advising had raised a big stack of SAFEs, then went out to hire a senior engineer and offered her a percentage of the company. He believed the number. She believed the number. But none of the pending SAFE conversion had been baked in, so what she was getting — after the SAFEs that had already been signed actually converted — was a fraction of what was on the page.
Everybody gets diluted, that’s the deal. But you should only be diluted by money raised after you showed up. Promising someone a percentage of something that’s already been committed to someone else is just a promise you’ll have to break in about eighteen months.
Friction was doing you a favor
Priced rounds are annoying. Lawyers, term sheets, an argument about pre-money versus post-money, an obligatory refresh of the option pool. And all of that annoyance forces you to do the math: you’re giving away eighteen percent of your company, and here’s what you’ll own when you’re done.
A SAFE lets you skip that. Which is wonderful, and which is why signing one feels like putting something on a credit card — every swipe is painless, and then the statement shows up months later with all of them on it at once.
So build the model. What does your cap table look like if you raise your priced round at $5 million? At $10 million? At $20 million? What if you raise another $750K in SAFEs first? Where does the option pool come from? You have to do it every single time you sign another one — because no individual SAFE is ever the problem, which means no individual SAFE is where you’ll catch it.
So... to get to the point... I would still do a SAFE.
I’d just make sure I was also asking: how much money do I actually need? Where will it take me? And will reaching my milestone make it easier — or harder — to raise the next round?
Those, rather than which type of investment paperwork to use, are the more important questions.
P.S. Do you have a question about starting or growing a business? Is there something specific you’re struggling with? I would love to help.
I’ve recently joined Wisen, a mentoring platform that has allowed me to dramatically expand the number of people I can help. If you’re interested in getting one-on-one personal advice from a real person, you can learn more at Wisen.com
Great article, I just signed my first SAFE this year, this info is definitely worth keeping in mind.
needed to read this! so helpful.